What’s On/Finance
Receiving supplier e-invoices in the UAE, and keeping your input VAT
Your e-invoicing provider will receive your suppliers' invoices as well as send yours. Here is how that works, what the input VAT rules now say, and the supplier checks that already apply.
E-invoicing is usually discussed as a sales topic, but it changes purchasing too. The accredited service provider you appoint receives invoices from your suppliers, from the print shop to the caterer to the contractor with a trade licence. The Ministry of Finance's guidelines say one provider covers both directions.
The journey of a supplier's invoice
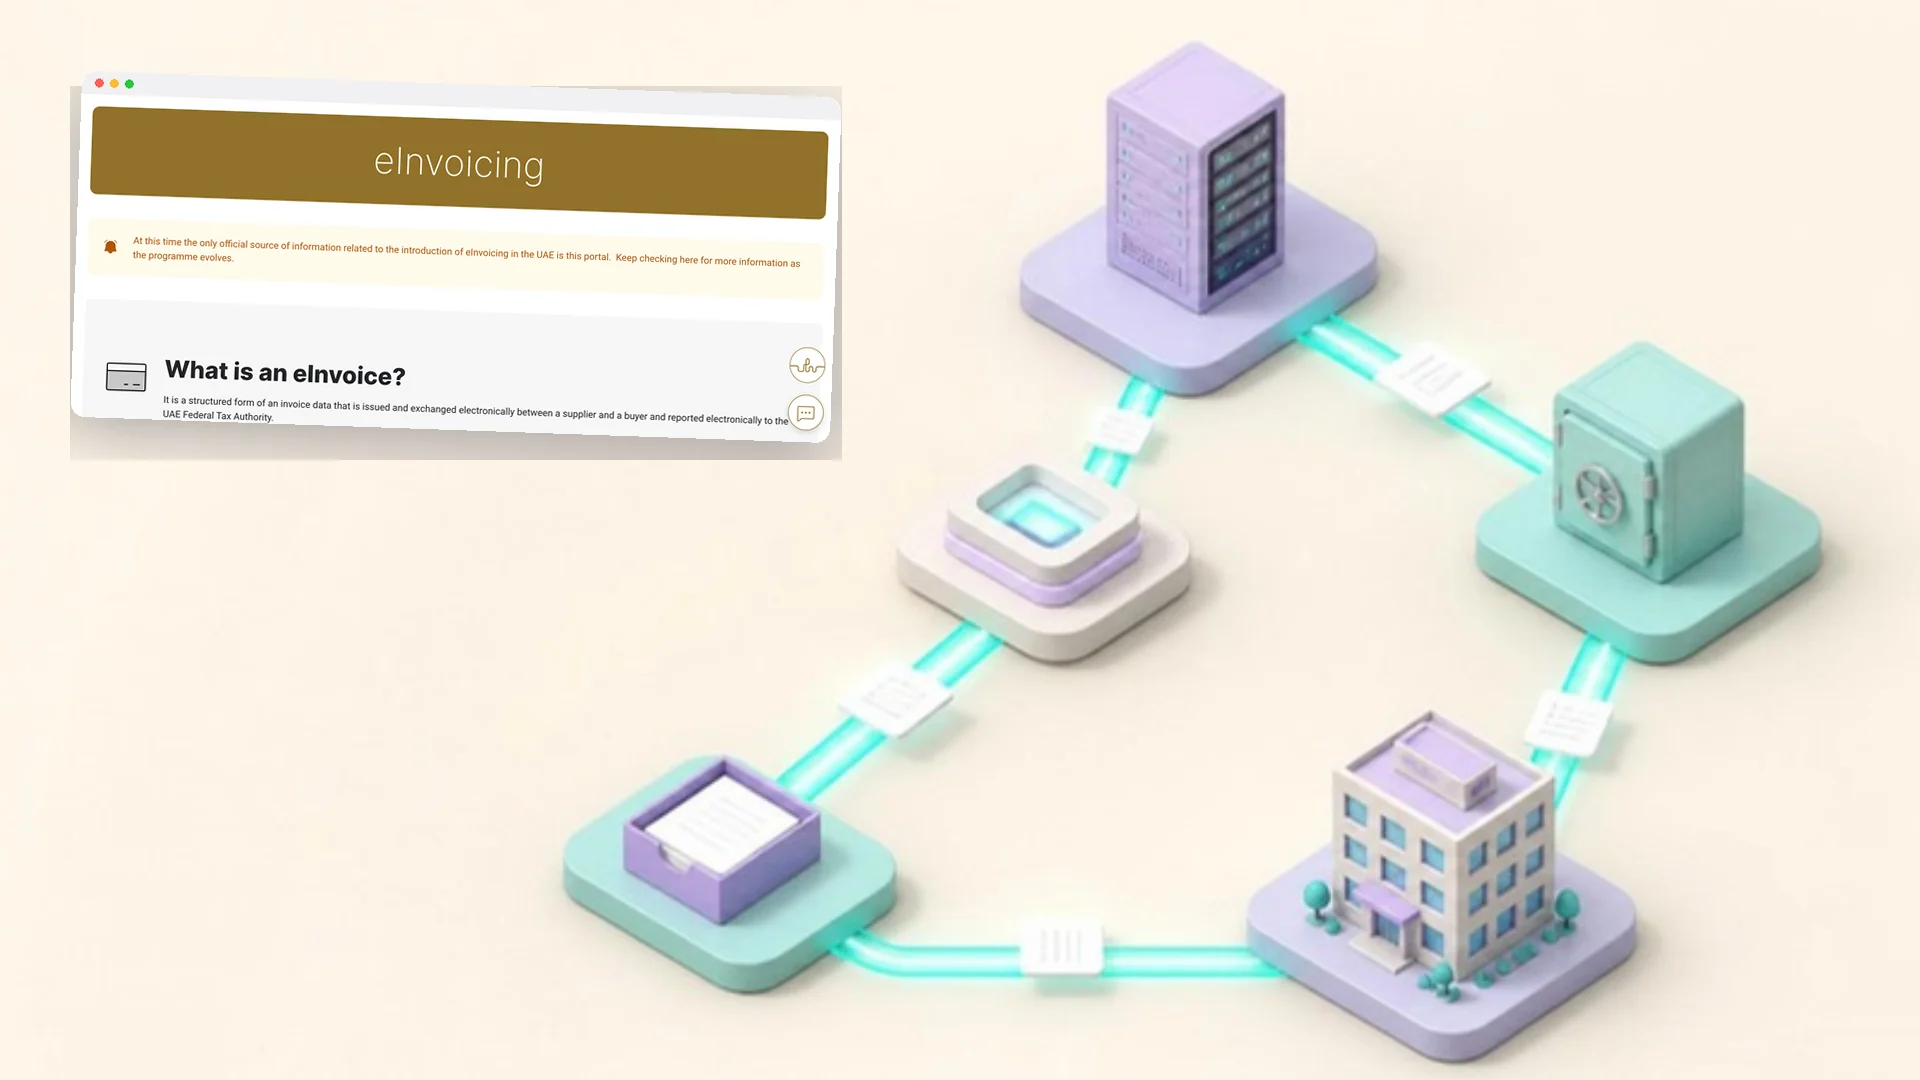
Your supplier's provider sends the invoice across the Peppol network to your provider, which validates it and reports its tax data to the Federal Tax Authority. An invoice that fails validation is rejected back to the supplier's provider and the FTA, and is not reported. What lands with you is structured data that accounting software can import directly.
What the input VAT rules say
- Under Article 55 of the VAT Decree-Law, input VAT is deducted in the first tax period in which you hold the tax invoice and have paid it, or intend to pay it within six months of the agreed date.
- Since October 2024, where an invoice must be or has been issued electronically, it must also be kept in line with the e-invoicing system.
- A claim missed in the first period can be made in the next one. Beyond that, the FTA expects a voluntary disclosure.
- The five-year limit introduced on 1 January 2026 is about using or refunding a VAT credit balance, not about claiming input VAT. A credit arising in January 2026 lapses on 31 January 2031.
Before everyone is live
Until a supplier's own phase starts, its invoices follow current rules, and its PDF tax invoice is what you claim on. A supplier that is live while you are not sends the e-invoice to a placeholder address and gives you an ordinary invoice as well. Because the e-invoicing condition only applies where an e-invoice is required or was issued, we read the rules as letting a PDF from a supplier that is not yet live support your claim. The FTA has not yet addressed that in-between case directly.
Overseas bills and advertising platforms
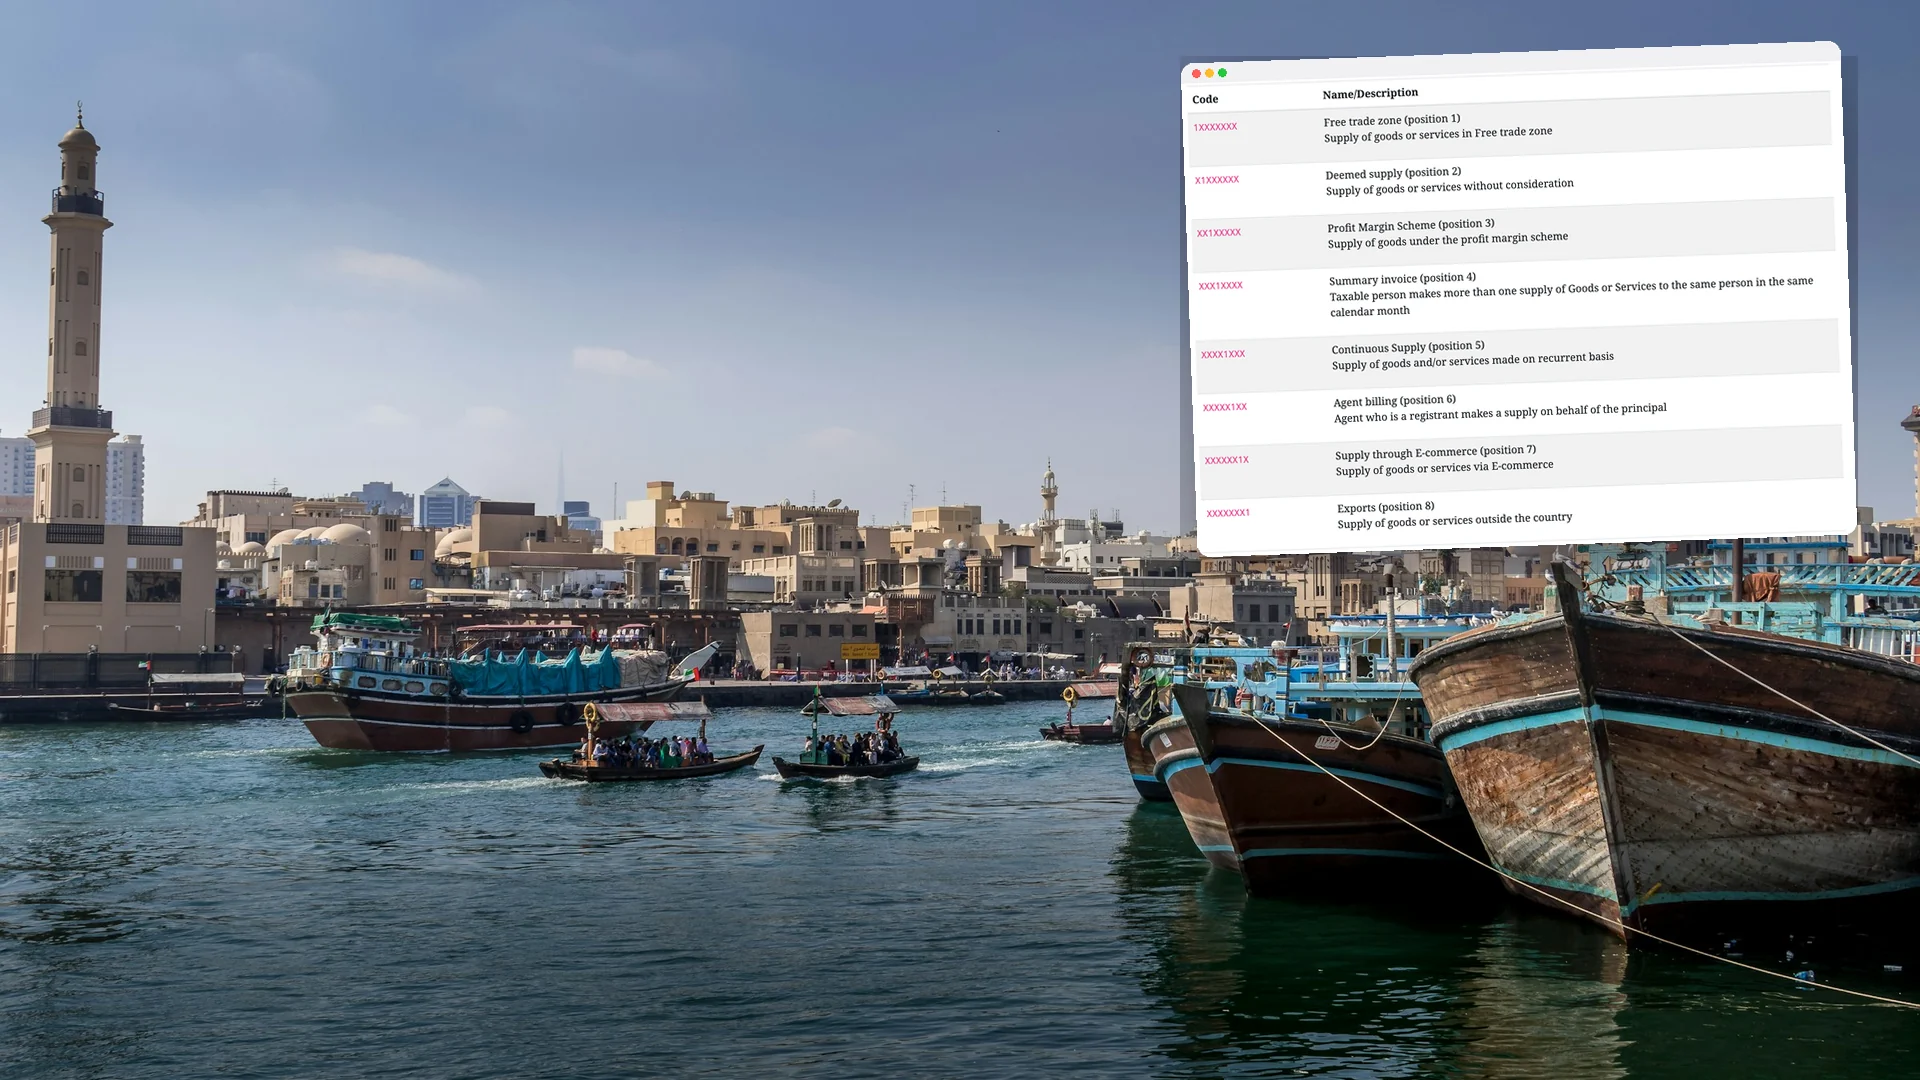
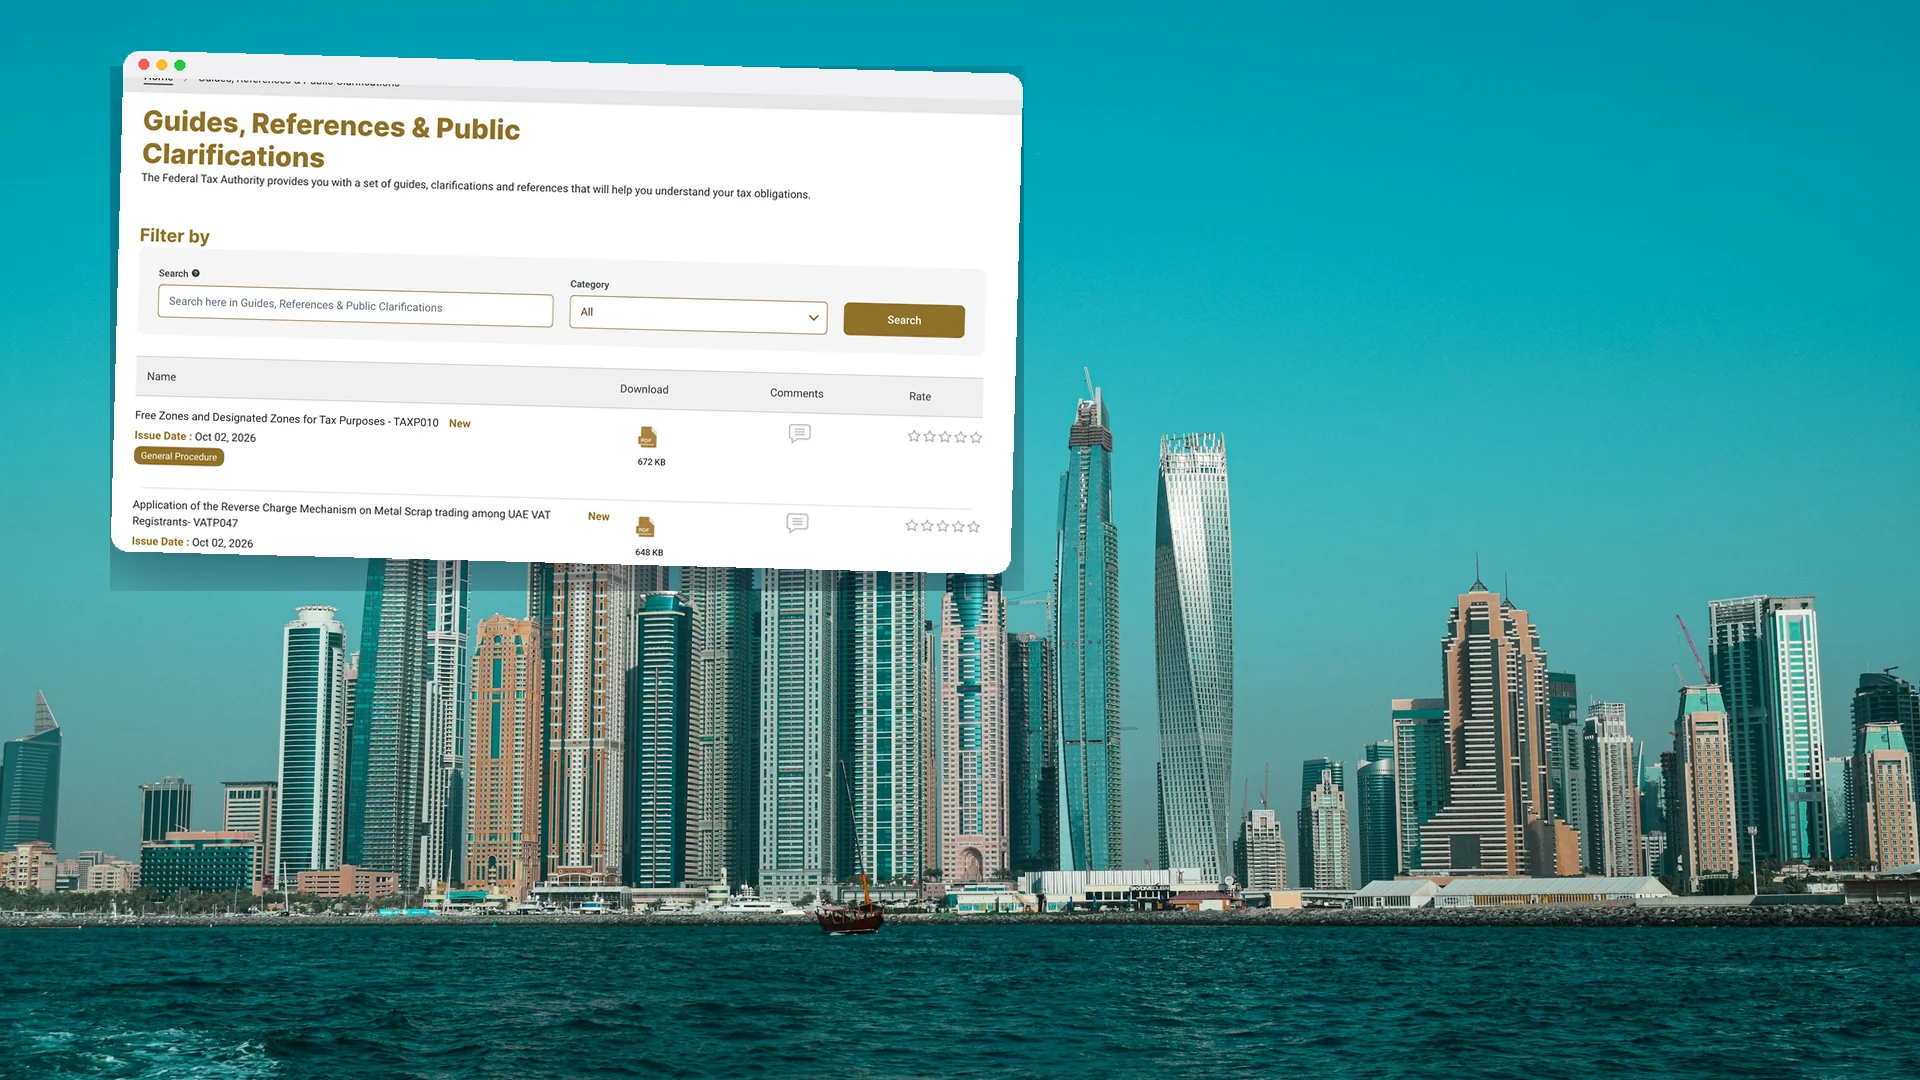
Bills from Meta, overseas freelancers or foreign software firms are imported services under the reverse charge, and the guidelines exclude them from e-invoicing. Since 1 January 2026 there is no self-invoice; you report the VAT in boxes 3 and 10 of your return and keep the supplier's invoice. The reverse charge category used on e-invoices is for certain domestic goods, such as electronics and scrap metal.
Checking your suppliers
From 1 January 2026, the FTA may refuse input VAT where a supply is part of a tax evasion chain and you knew or should have known, and failing to check a supplier counts as should have known. FTA Decision 13 of 2026, effective 1 October 2026, lists the checks:
- Confirm each supplier's identity, incorporation and address, and look for warning signs.
- For suppliers above AED 375,000 over 12 months, also obtain a UAE bank's confirmation of their account and review public feedback or press coverage.
- Pay electronically, record the checks, keep a written policy and repeat the checks every 12 months.
- Supplies below AED 10,000 are excluded, unless the supplier passes AED 100,000 in a year.
Cabinet Decision 149 of 2026, in force from the same date, also blocks input VAT on cash payments above a value the Minister is to set. We could not find that value published in early October.
Next steps
- Ask prospective providers how received invoices flow into your accounting software.
- Notify your provider within five business days of changes to your registered details, or face AED 1,000 a day.
- Find out when your main suppliers will start e-invoicing.
- Document your supplier checks now, since they already apply.
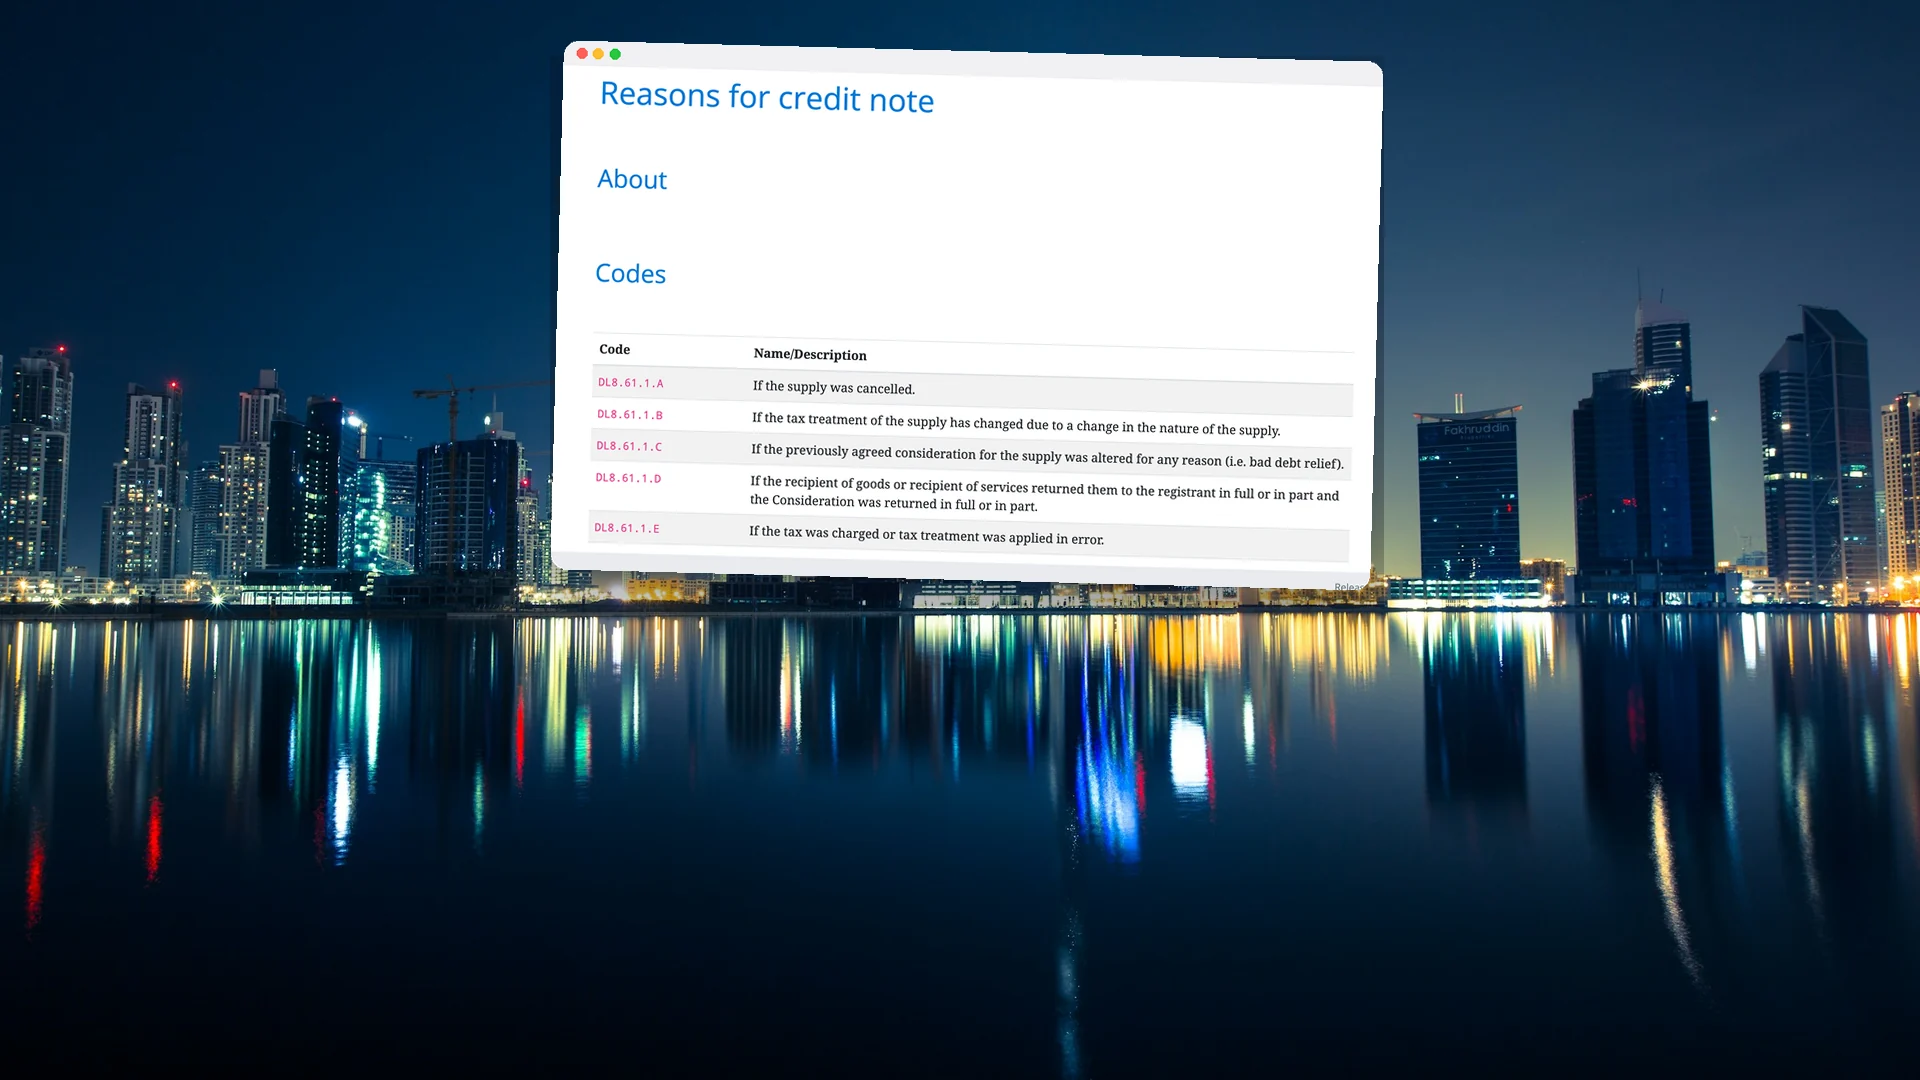
Errors on a supplier's invoice are corrected by the supplier with an electronic credit note. If you want help setting up a supplier checking routine that will stand up to the FTA, speak to ALXO.