What’s On/Finance
Invoicing overseas customers from the UAE: VAT and e-invoicing
Selling services to a customer abroad does not take the invoice out of UAE e-invoicing. What matters is whether it qualifies for zero rating, how the currency is shown and how the file is flagged.
Many UAE businesses sell services abroad, to a parent company in London, a distributor in Riyadh or a customer in Singapore. E-invoicing covers those sales too. The Ministry of Finance's guidelines say an export tax invoice should be issued as an electronic invoice, and the example the Ministry chose is a UAE IT company billing a customer in France.
The zero rating tests
Exported services are zero-rated under Article 45 of the VAT Decree-Law, with the detail in Article 31 of the Executive Regulation, amended in November 2024. The common route requires all three:
- The customer has no residence in the UAE or another implementing state, and is outside the UAE while the service is performed. A visit under 30 days that has nothing to do with the service is ignored.
- The service is not directly linked to UAE property or to goods located in the UAE.
- The service is not one that the law treats as performed in the UAE, a category that includes cultural, artistic, sporting, educational and similar services.
There is also a separate route for services performed entirely outside the UAE.
Common reasons it fails
- A representative of the customer is in the UAE while the work is done. The FTA's guide on exported services, VATP019, says the zero rate is then lost.
- The customer has a UAE branch more closely tied to the work, which makes the customer UAE resident.
- Someone in the UAE, such as local staff of the customer, is foreseeably the one receiving the service and could not fully recover the VAT.
- The facts cannot be established. The FTA's answer is to charge the standard rate, so keep contracts, addresses and records of where the customer was.
Customers in the Gulf
Customers in Saudi Arabia, Oman or Kuwait are treated like any other foreign customer for now. The FTA does not recognise another GCC state as an implementing state, so the same tests and the same export invoice apply.
Currency
Article 69 of the Decree-Law converts foreign-currency amounts into dirhams at the UAE Central Bank's rate on the date of supply. An e-invoice spells this out: each line carries its dirham amount, the exchange rate is stated, and VAT and the total with VAT are shown in AED, whatever currency the invoice uses.
How the file changes
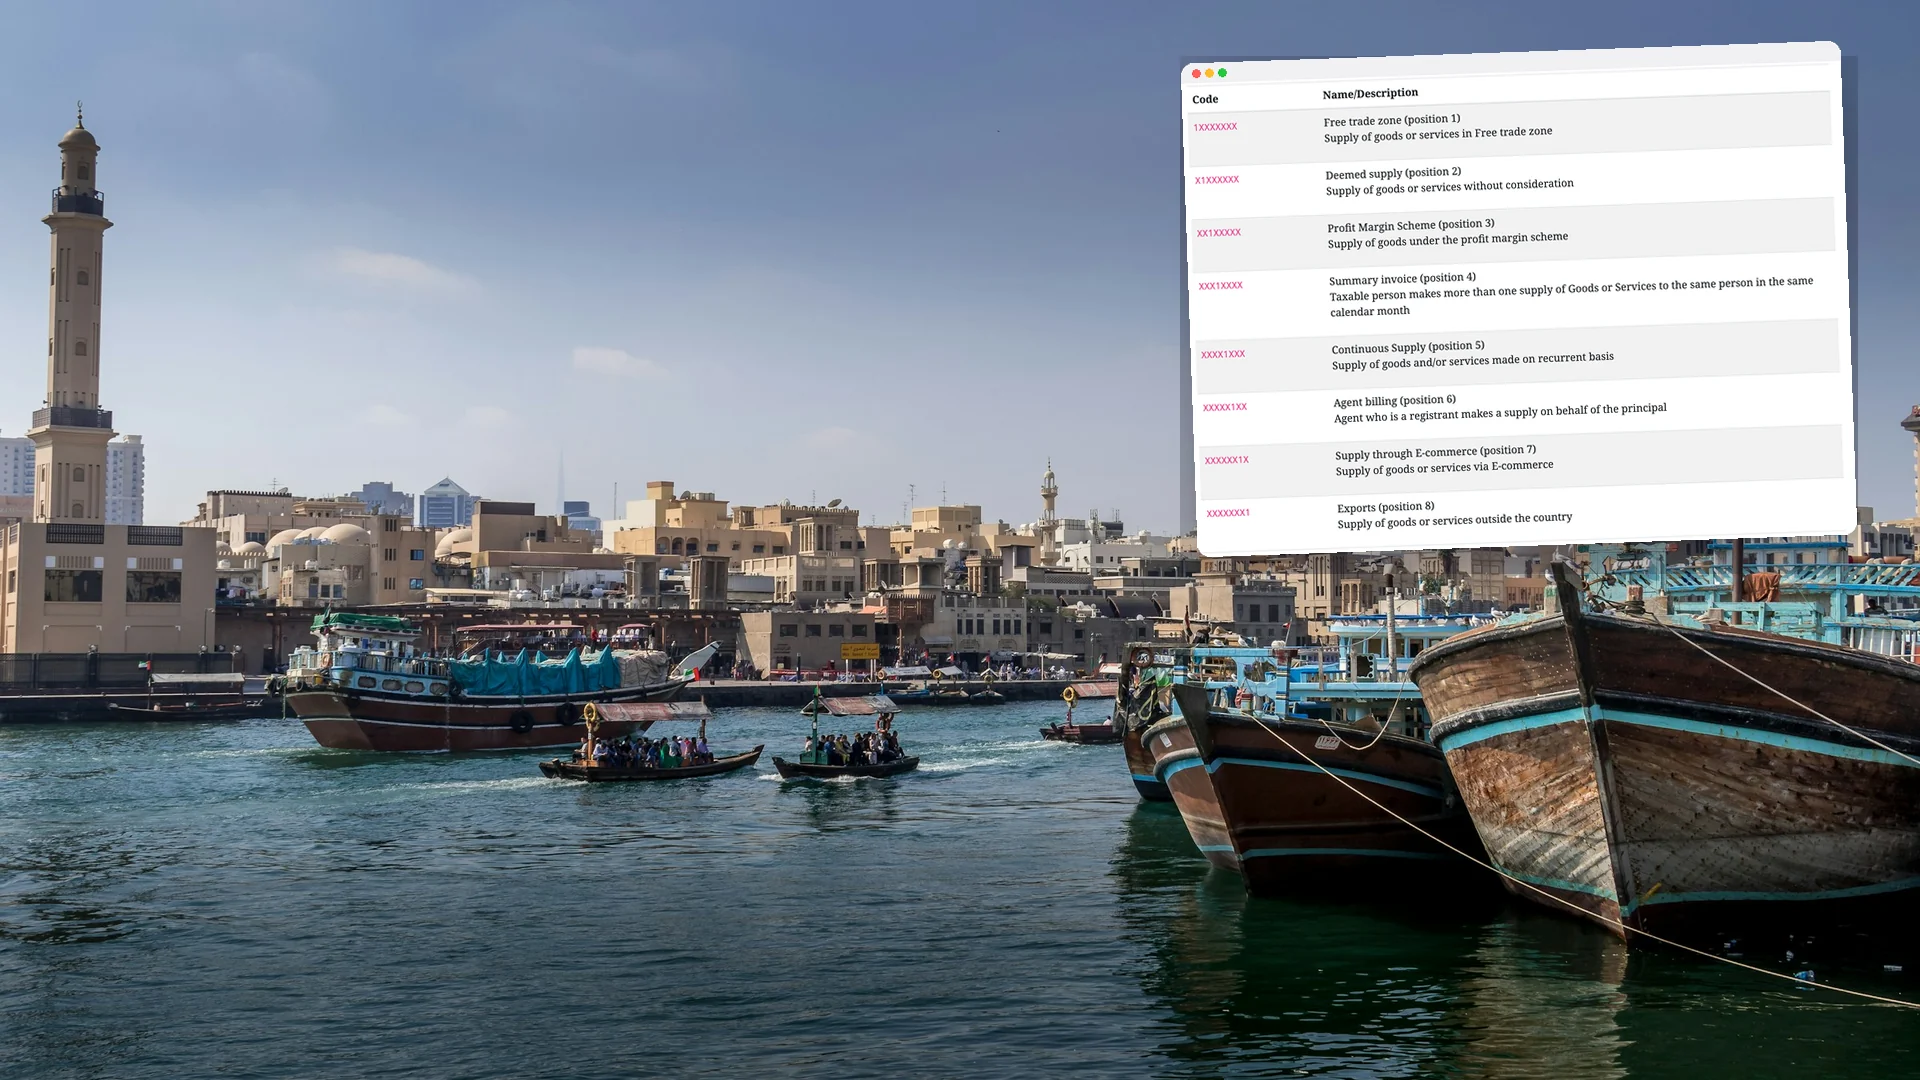
- The eighth transaction flag marks the invoice as an export.
- With that flag on, a delivery address outside the UAE is required.
- Customers without a Peppol ID, which is most overseas customers, are addressed to 0235:9900000099. The invoice is reported to the FTA and the customer gets a copy outside the network, usually by email.
- Zero rating does not excuse the tax invoice. The relief for wholly zero-rated supplies does not apply to electronic invoicing.
The other direction
Services you buy from abroad, such as advertising platform bills or a foreign consultant's fee, fall under the reverse charge, and the guidelines exclude them from e-invoicing. Since 1 January 2026 no self-invoice is needed for them, though the VAT still has to be accounted for and the supplier's invoice kept.
International invoicing is where small set-up mistakes repeat on every invoice. If you would like ALXO to look over how yours are prepared, get in touch.